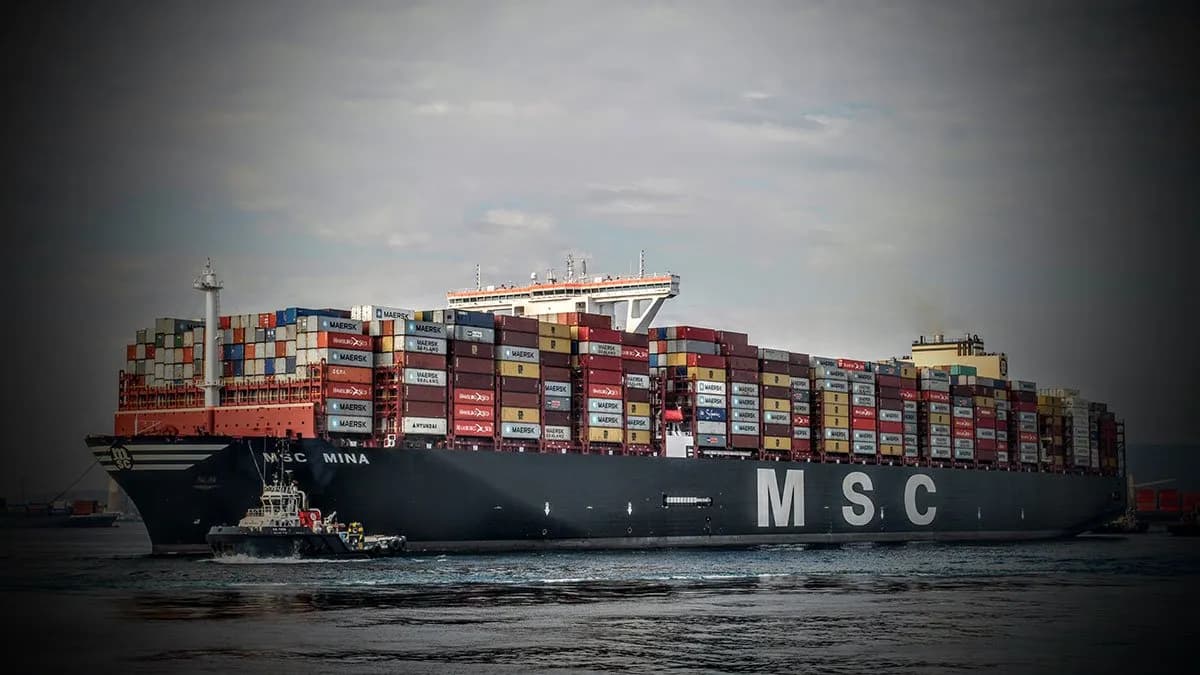
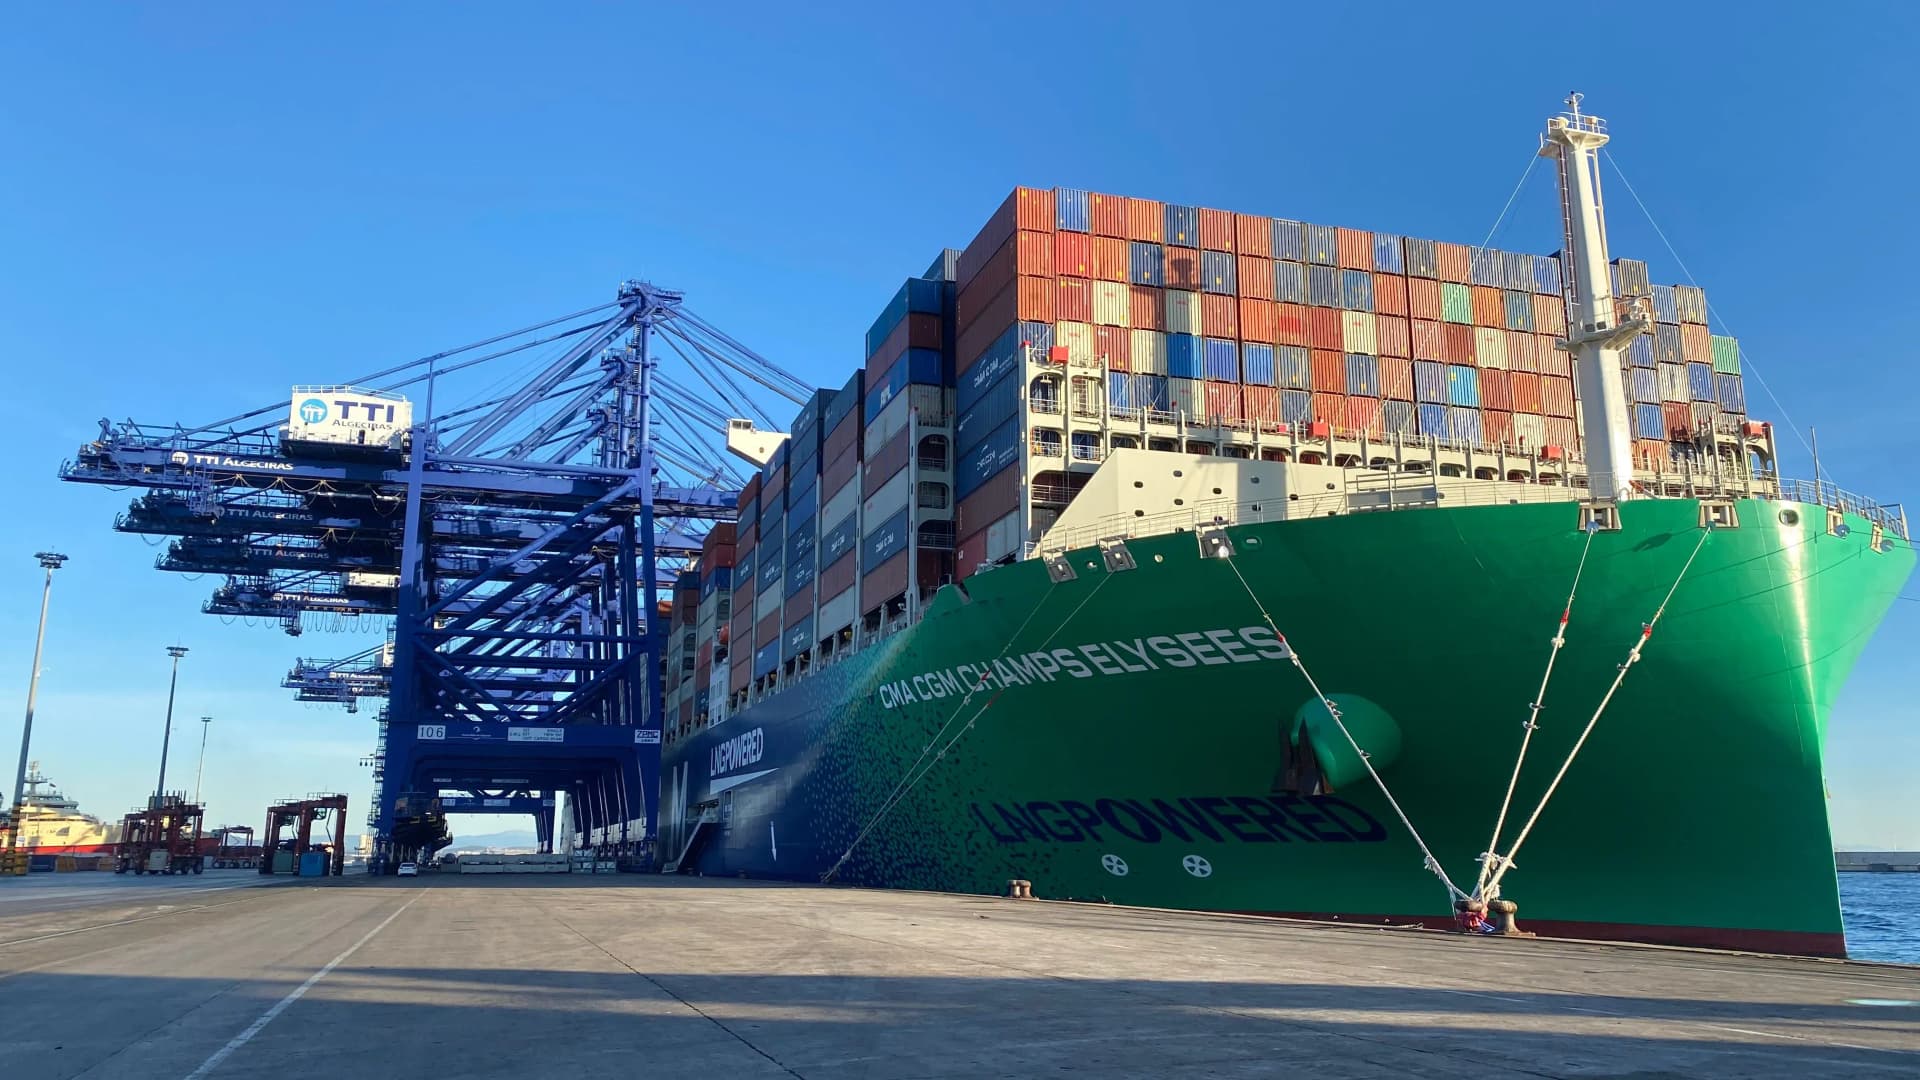
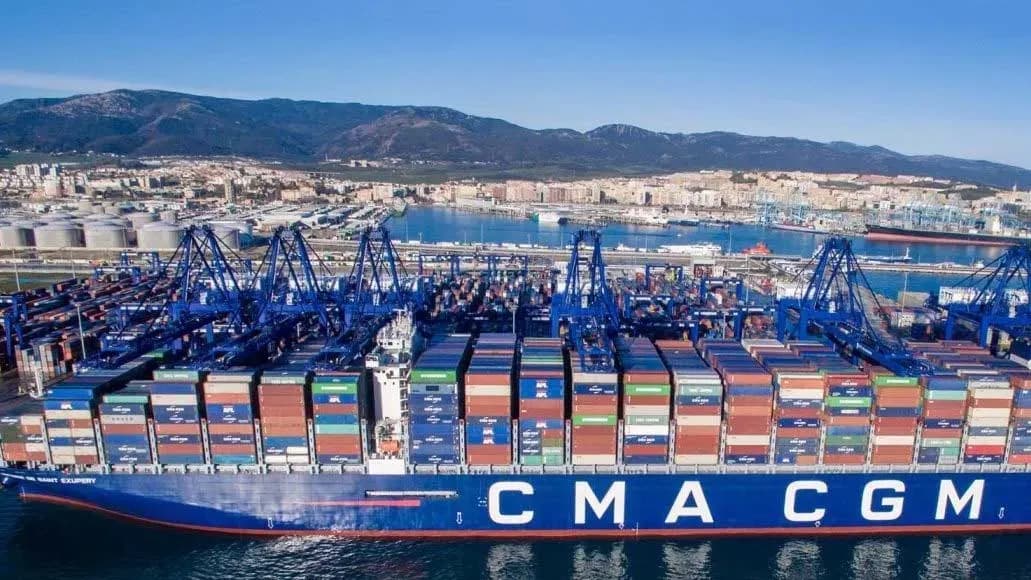
The maritime container routes between Europe and the two coasts of South America remain under the almost total dominance of four European shipping companies. MSC, Maersk, CMA CGM, and Hapag-Lloyd jointly operate 93.3% of all capacity deployed in these corridors, according to Alphaliner data for the month of April.
In the face of this hegemony, Asian shipping lines maintain a reduced presence. COSCO Shipping and Ocean Network Express (ONE) are the only companies of that origin operating between Europe and the eastern (ECSA) and western (WCSA) coasts of South America, with a joint market share of 6.2%. The remaining 0.5% is held by two specialized operators.
In total, 99 container ships operated in April on the routes between Europe and both South American coasts, with a combined capacity of 710,530 TEUs, equivalent to 2.1% of the world cellular fleet of containers. The Europe-ECSA route had 49 ships and a capacity of 369,573 TEUs, slightly above the Europe-WCSA route, which recorded 50 ships and 340,957 TEUs. The average size of the ships on the route to the east coast was 7,542 TEUs, compared to 6,819 TEUs on the route to the west coast.
The most significant change in the allocation of shares has occurred on the Europe-ECSA route, where MSC has become the market leader after increasing its capacity by 4.1% year-on-year, reaching a share of 34.8%. The Geneva-based shipping company has thus dethroned Maersk, which had until now held the top position in this corridor.