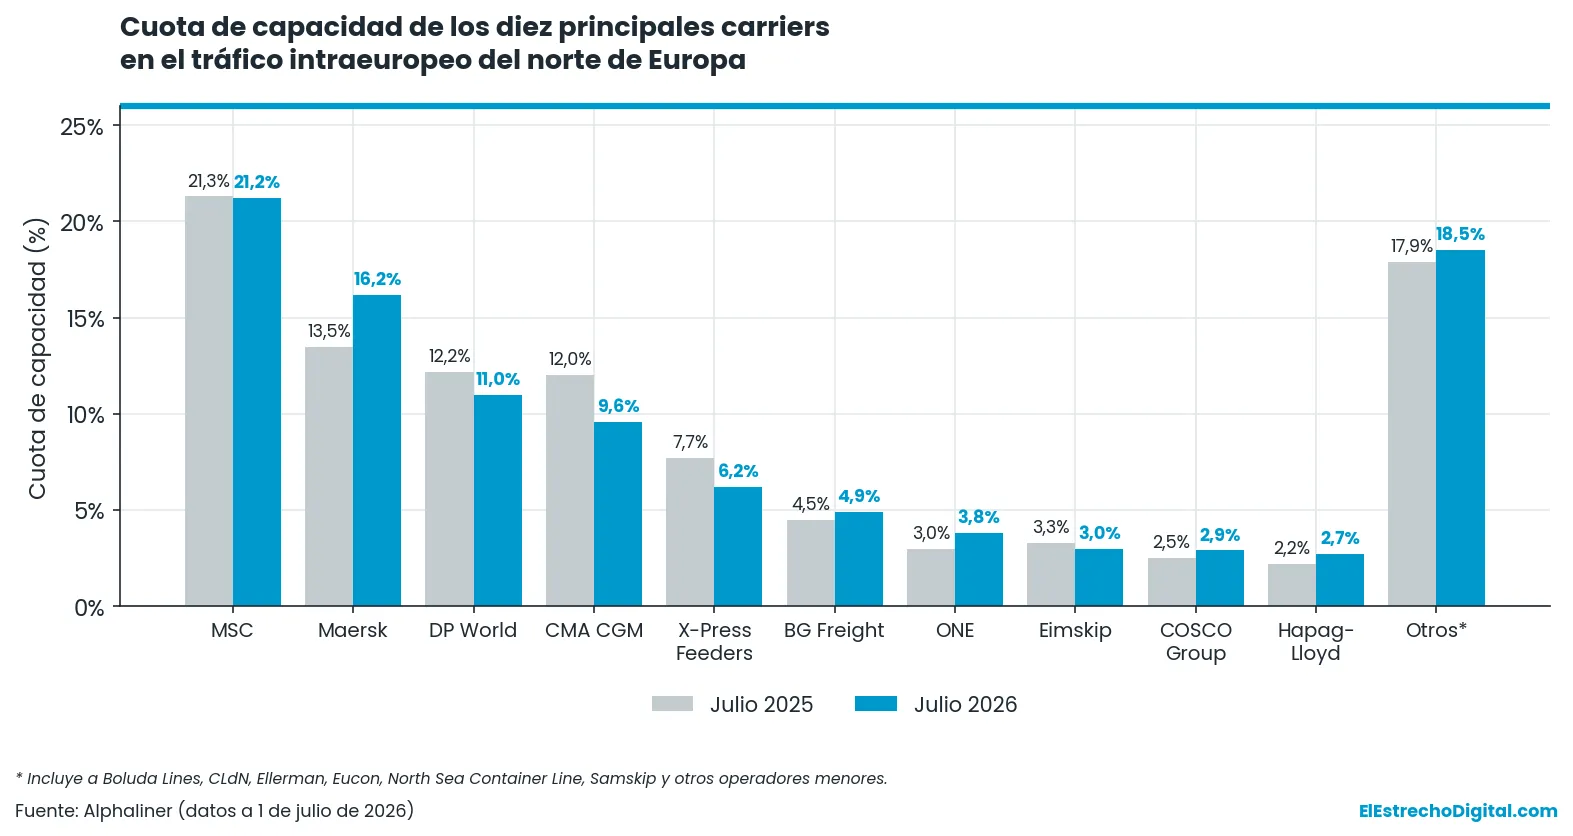
Maersk records the highest growth in capacity and market share among shipping companies operating in the northern intra-European segment over the past twelve months, according to data published by the consulting firm Alphaliner as of July 1, 2026. The Danish company raised its share to 16.2%, with 50,800 TEUs deployed, compared to 13.5% (39,800 TEUs) a year earlier, a gain of 2.7 points, the largest of any operator in the segment.
Traffic in the northern intra-European sector grew by 6.8% in capacity, nearly 20,000 TEUs more than in July 2025. Shipping companies deployed 243 vessels compared to 235 the previous year, with a slightly larger average size: 1,294 TEUs per vessel compared to 1,253 TEUs twelve months prior. The overall market remains dominated by MSC, which retains the top position with a share of 21.2%, nearly identical to the 21.3% from a year ago. The Geneva-based company added 6.2% in capacity, a pace below the average growth rate of the segment, although it retains a strong lead over other operators.
Maersk's leap comes from the "hub and spoke" model that the company launched last year with its partner in the Gemini alliance, Hapag-Lloyd. This scheme concentrates trans-ocean traffic in a small number of northern European base ports and uses its own feeder services to redistribute cargo to the rest of the Atlantic and Baltic terminals, which explains the disproportionate increase in capacity and share of the Danish shipping company in this segment compared to the overall market.
DP World retains third place in the intra-European ranking, ahead of CMA CGM and X-Press Feeders. The Emirati giant in ports, maritime transport, and logistics recorded a share of 11.0%, down from 12.2% the previous year. At the end of 2025, the group withdrew the Unifeeder brand, with which it had been providing feeder services in northern Europe until then, and integrated the network under its own corporate banner.